Sustainable procurement is becoming a core part of professional purchasing. It is no longer enough to buy products or services at the best possible price. Companies increasingly need to understand how procurement decisions affect the environment, supply chains, working conditions, life cycle costs and long-term security of supply.
Sustainable purchasing therefore considers environmental, social and economic criteria at an early stage: when defining demand, writing specifications, selecting suppliers, preparing tenders, negotiating contracts and measuring performance. This turns sustainability in procurement from a later correction into a structured part of purchasing strategy.
SJL Management & Consulting supports companies in aligning procurement processes strategically, assessing supplier structures and embedding purchasing effectively into organisation, steering and implementation. More about our approach: Our Services.
What is sustainable procurement?
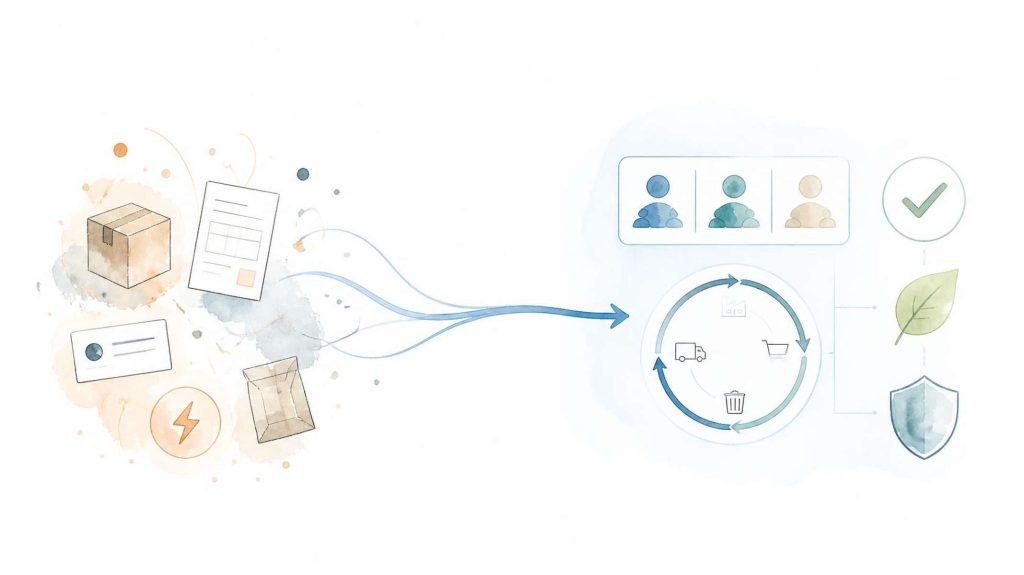
Sustainable procurement means selecting products, services and suppliers in a way that considers environmental, social and economic impacts across the entire life cycle. The purchase price is only one part of the decision. Usage, quality, risk, supplier conditions, energy consumption, maintenance and disposal are also relevant.
Short definition:
Sustainable procurement is a purchasing approach in which companies systematically consider environmental impact, social standards, life cycle costs and supplier risks alongside price, quality and availability.
Sustainable procurement explained simply
In practice, sustainable procurement means that purchasing does not start and end with the offer price. Before a tender is issued, the company checks which requirements are appropriate. Should the product be particularly durable? Are recycled materials possible? What energy or maintenance costs will arise? Which social standards apply at the supplier? Are there risks in the supply chain?
Sustainability in procurement is therefore not only an ESG topic and not only a compliance task. It influences cost, quality, delivery capability, reputation and risk management.
Sustainable purchasing vs traditional procurement
Traditional procurement often focuses strongly on price, availability and contract terms. Sustainable purchasing broadens this perspective.
| Approach | Focus | Typical decision |
|---|---|---|
| Traditional procurement | Price, quality, delivery time | Which supplier can deliver reliably at a competitive price? |
| Sustainable procurement | Environmental impact, social responsibility and economic value across the life cycle | Which solution is more economical, lower risk and more sustainable in the long term? |
The difference is not that cost becomes irrelevant. Rather, cost is assessed more completely. A low-cost product can become more expensive over its lifetime if energy consumption, maintenance, failures or disposal create high follow-up costs.
For more on the strategic role of purchasing, see the SJL article Strategic Procurement: Tasks, Goals and Relevance.

Why sustainable purchasing is becoming more important for companies
Sustainable purchasing is becoming more important because companies are increasingly expected to demonstrate how they manage resources, suppliers, risks and social requirements. Expectations from customers, employees, business partners and regulators are also rising.
For procurement, this means sustainability must be translated into practical decisions. General commitments are not enough. Companies need specific criteria, clear responsibilities and measurable steering.
Sustainability in procurement is more than compliance
Compliance can be an important trigger, but it is not the only reason for sustainable procurement. Companies benefit most when sustainability in procurement is connected to strategic business goals.
These include:
- more resilient supply chains
- lower dependency on critical suppliers
- better transparency across categories and risks
- lower follow-up costs through more durable products
- stronger decision-making in tenders
- better supplier relationships
- clearer ESG and sustainability criteria
Sustainability therefore becomes part of professional procurement steering. It complements price and quality targets rather than replacing them.
Life cycle costs instead of purchase price only
Life cycle costs are a central lever in sustainable procurement. They show that the lowest purchase price is not automatically the most economical decision.
Relevant cost factors include:
- purchase price
- energy consumption
- maintenance costs
- repairs
- spare parts
- useful life
- failure risks
- disposal costs
- recyclability
Life cycle costs are especially relevant for IT, machinery, vehicles, building technology, lighting and operating equipment. In these categories, usage costs across the full life span can be more important than the initial purchase price. The German Environment Agency provides a useful overview of life cycle costs in environmentally friendly procurement.
Criteria for sustainable procurement
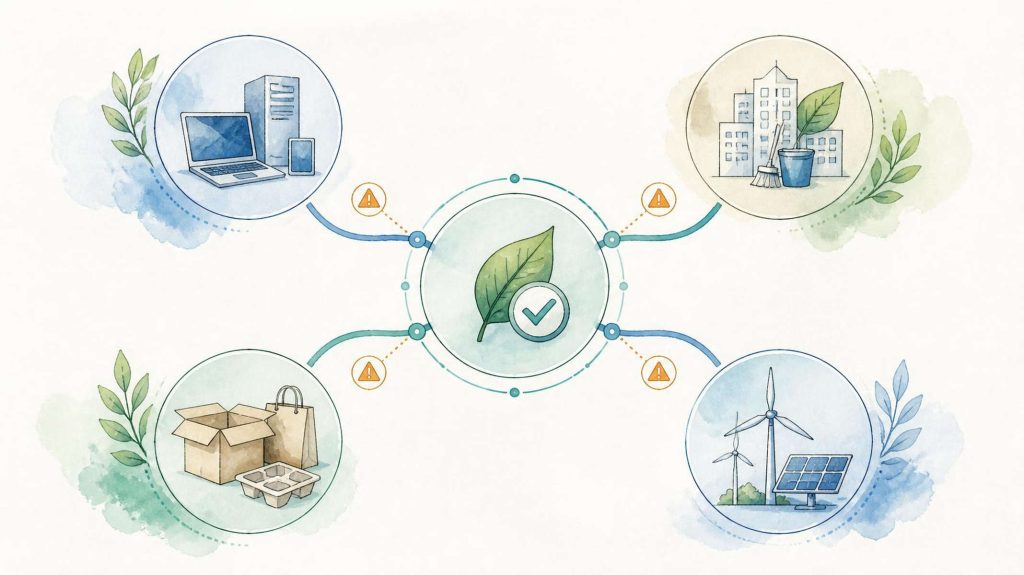
Sustainable procurement is based on environmental, social and economic criteria. Which criteria matter most depends on the industry, category, supplier market and business objectives.
| Dimension | Criteria | Examples |
| Environmental | Energy efficiency, CO₂, resource consumption, recycling, packaging, durability | Green electricity, recycled paper, long-lasting IT, reusable packaging |
| Social | Human rights, working conditions, occupational safety, fair supply chains | Supplier self-assessments, audits, social standards |
| Economic | Life cycle costs, quality, security of supply, supplier stability | Total cost of ownership, maintenance costs, failure risks |
Environmental criteria
Environmental criteria assess how products, services or suppliers affect the environment and the use of resources. This includes energy consumption, emissions, material use, packaging, recyclability and disposal.
Typical procurement questions include:
- Are there more energy-efficient alternatives?
- Can recycled or recyclable materials be used?
- Is the product durable and repairable?
- What packaging and transport emissions are involved?
- Are environmental labels or reliable evidence available?
- Can waste be reduced or materials kept in circulation?
Environmental criteria should not be considered in isolation. A product is not automatically more sustainable just because one feature is better. The overall impact across use, supply chain and life span matters.
Social criteria
Social criteria relate to working conditions, human rights, occupational safety, fair pay, equality and responsible supply chains.
For procurement, this can include:
- defining supplier requirements
- including supplier codes of conduct
- checking evidence and self-assessments
- assessing risks by country, industry and category
- developing critical suppliers
- documenting contractual requirements clearly
Especially in global supply chains, it is not enough to formulate social criteria in general terms. Companies need a risk-based approach: where are the greatest risks, which suppliers are most relevant and which evidence is required?
Economic criteria
Sustainable procurement must also be economically viable. Economic criteria ensure that sustainability is not treated separately from cost, quality and security of supply.
Relevant criteria include:
- life cycle costs
- delivery capability
- quality stability
- supplier financial stability
- innovation capability
- availability of alternatives
- maintenance and service costs
- risk costs in the event of failure
Professional sustainable purchasing does not mean always choosing the most environmentally advanced option regardless of cost. It means making long-term, robust and economically sensible decisions.
For more on the connection between cost, structure and purchasing levers, see the SJL article Cost Optimisation in Procurement.
ISO 20400: guidance for sustainable procurement
ISO 20400 is an international guidance standard for sustainable procurement. It helps organisations understand how sustainability can be integrated into procurement strategy, processes, supplier relationships and decision-making structures.
The standard is not only relevant for public-sector organisations or large corporations. It can serve as a practical orientation for organisations of different sizes and sectors. The official overview is available from the International Organization for Standardization on ISO 20400.
What does ISO 20400 cover?
ISO 20400 describes how sustainable procurement can be embedded in organisations. It is not focused only on individual products, but on the overall management approach: strategy, governance, risk assessment, stakeholders, supply chains and procurement processes.
For companies, ISO 20400 is particularly useful because it supports the structured integration of sustainability into existing purchasing processes. This includes:
- roles and responsibilities
- sustainable procurement objectives
- integration into procurement policies
- supply chain risk analysis
- supplier evaluation
- tender requirements
- performance measurement
- continuous improvement
Is ISO 20400 a certification?
ISO 20400 should be understood as guidance, not as a classic certification standard. Companies can use it as a framework to build and improve sustainable procurement.
For communication, it is important not to claim that a company is certified according to ISO 20400 unless there is reliable evidence. A more accurate formulation is that procurement processes can be aligned with the principles of ISO 20400.
Implementing sustainable procurement in business: 7 steps
Sustainable procurement does not succeed through individual purchasing decisions alone. It requires structure, prioritisation and clear implementation steps.
1. Analyse the current situation and categories
The first step is transparency. Companies should assess which categories, suppliers and procurement volumes are most relevant.
Important questions include:
- Which categories have high environmental or social relevance?
- Where are the highest spend areas?
- Which suppliers are critical?
- Where is sustainability data missing?
- Which contracts already include sustainability requirements?
- Where are short-term improvements possible?
This analysis prevents sustainability in procurement from starting too broadly or too vaguely.
2. Define sustainability goals in procurement
Sustainability goals should be specific enough for procurement teams to work with. General statements such as “we want to buy more sustainably” are not enough.
More practical goals include:
- assessing selected categories against sustainability criteria
- systematically recording supplier risks
- considering life cycle costs in selected categories
- reducing packaging volumes
- checking sustainable alternatives in tenders
- integrating ESG criteria into supplier evaluations
These goals must fit the company strategy, procurement organisation and available data.
3. Prioritise relevant product groups
Not every product group is the right starting point. A useful approach is to prioritise by impact, risk and feasibility.
Frequently relevant areas include:
- energy and electricity
- fleet and mobility
- IT hardware
- office supplies
- packaging
- workwear
- cleaning and facility services
- machinery and technical equipment
- logistics services
- external services
A clear category strategy in procurement helps translate sustainability goals into specific categories.
4. Integrate sustainability criteria into tenders
Sustainability must be embedded where purchasing decisions are made: in specifications, tenders, evaluation matrices, contracts and supplier requirements.
Possible approaches include:
- defining minimum requirements
- weighting sustainability criteria
- checking evidence and certificates
- considering life cycle costs
- including environmental and social standards in contracts
- agreeing supplier development measures
- defining reporting obligations
Criteria should be realistic and verifiable. Vague requirements make evaluation difficult and often create discussions later.
5. Evaluate and develop suppliers
Sustainable procurement becomes particularly effective when it is connected to supplier management. Suppliers should not be assessed only by price and delivery reliability, but also by relevant sustainability and risk criteria.
These may include:
- environmental management
- energy and resource efficiency
- social standards
- occupational safety
- evidence and documentation
- supply chain risks
- compliance
- innovation capability
- willingness to improve
Not every supplier has to be perfect immediately. The key is to identify critical suppliers, make expectations transparent and agree development steps.
For more on this, see the SJL article Supplier Management & Supply Chain Resilience.
6. Consider life cycle costs
Life cycle costs should be used wherever usage and follow-up costs are relevant. This is especially important for products with energy consumption, maintenance needs, spare parts or disposal costs.
A simple assessment can include the following cost types:
| Cost type | Examples | Relevance |
| Purchase | Purchase price, implementation, transport | Initial procurement costs |
| Use | Energy, consumables, operating effort | Ongoing operating costs |
| Maintenance | Service, repairs, spare parts | Costs for availability and useful life |
| Risk | Failure, quality issues, delivery delays | Potential follow-up costs |
| Disposal | Take-back, recycling, waste costs | Costs at the end of use |
This makes it clearer which solution is more economical over its full useful life.
7. Define KPIs and responsibilities
Sustainability in procurement needs measurable steering. Without KPIs, it remains unclear whether measures are working.
| KPI | Meaning | Benefit |
| Share of evaluated suppliers | Suppliers with a sustainability or ESG assessment | Shows transparency in supplier management |
| Share of sustainable categories | Categories with defined sustainability criteria | Makes progress in strategic procurement visible |
| Life cycle cost assessments | Share of relevant purchases with life cycle assessment | Supports more economical decisions |
| Sustainability criteria in tenders | Share of tenders with verifiable criteria | Shows integration into procurement processes |
| Audit or evidence rate | Share of suppliers assessed or documented | Strengthens risk management and compliance |
| Share of recyclable or durable products | Product-related sustainability quality | Supports resource conservation and circular economy |
Effective procurement controlling helps ensure that these KPIs are not merely collected, but translated into decisions.
Common barriers to sustainable procurement
Sustainable procurement rarely fails because of a lack of intention alone. More often, companies lack data, processes, clear responsibilities or practical criteria.
Missing data on suppliers and products
Many companies do not have enough sustainability data on suppliers, products or categories. Without reliable data, evaluation becomes difficult.
A pragmatic starting point is to prioritise critical categories and key suppliers first. Data requirements can then be expanded step by step.
Conflicting goals between cost, quality and sustainability
Sustainable alternatives may appear more expensive at first glance. That is why it is important not to consider the purchase price alone. Useful life, energy consumption, service costs and failure risks can change the overall picture.
At the same time, trade-offs are real. Procurement, specialist departments and management should therefore define clear evaluation logic.
Unclear responsibilities in procurement
Sustainable procurement involves purchasing, specialist departments, compliance, sustainability management, finance and suppliers. Without clear responsibilities, implementation quickly becomes fragmented.
A well-structured procurement organisation defines:
- who sets criteria
- who assesses suppliers
- who checks evidence
- who manages tenders
- who documents decisions
- who measures progress
For more on roles and governance, see the SJL article Procurement Organisation.
Checklist: is your procurement set up sustainably?
These questions provide an initial assessment:
- Are sustainability goals defined for procurement?
- Have relevant categories been prioritised?
- Are environmental, social and economic criteria clearly distinguished?
- Are life cycle costs considered in suitable procurement decisions?
- Are supplier requirements clearly defined?
- Are sustainability criteria integrated into tenders?
- Are suppliers assessed against ESG or sustainability criteria?
- Are responsibilities for sustainable procurement clearly assigned?
- Is progress measured through KPIs?
- Are specialist departments involved in developing criteria?
- Are trade-offs between cost, quality and sustainability assessed transparently?
- Is there a roadmap for the next categories?
If several of these questions remain unanswered, a structured current-state assessment is usually worthwhile.
When external support makes sense
External support can be valuable when sustainable procurement should not only be described conceptually, but implemented in everyday purchasing.
This is especially relevant when:
- categories need to be reassessed
- supplier data is missing
- ESG requirements must be integrated into tenders
- procurement strategy and sustainability goals need to be connected
- supplier management and risk management need to be developed further
- KPIs and responsibilities are unclear
- short-term implementation capacity is needed in procurement
SJL Management & Consulting supports companies in building effective procurement organisations, assessing supplier structures and integrating sustainable procurement pragmatically into processes, steering and implementation.
If short-term purchasing responsibility or implementation capacity is required, interim management in procurement can also be a suitable option.
Conclusion: sustainable procurement needs structure, not just good intentions
Sustainable procurement becomes effective only when environmental, social and economic criteria are systematically embedded in purchasing decisions. Individual sustainable products are not enough if processes, supplier evaluation, category strategy and KPIs are missing.
For companies, this means sustainable purchasing must be practical. It needs clear priorities, verifiable criteria, realistic goals and a steering model that considers cost, quality, delivery capability and sustainability together.
When sustainable procurement is anchored in procurement strategy, supplier management and procurement controlling, it creates more than transparency. It strengthens risk management, economic resilience and the long-term future readiness of purchasing.
Embed sustainable procurement effectively in purchasing
Would you like to integrate sustainability into procurement not only as documentation, but as a practical part of categories, supplier evaluation and purchasing processes?
SJL Management & Consulting supports you in implementing sustainable procurement pragmatically, measurably and in line with your business objectives.
FAQ on sustainable procurement
What is sustainable procurement?
Sustainable procurement means selecting products, services and suppliers not only by price and availability, but also by environmental, social and economic impacts across the full life cycle.
What is the difference between sustainable procurement and sustainable purchasing?
The terms are often used in a similar way. Sustainable procurement describes the full process from demand and specification to supplier selection and evaluation. Sustainable purchasing often refers to the practical buying decision using sustainability criteria.
Which criteria are part of sustainable procurement?
Important criteria include energy and resource efficiency, CO₂ impact, recyclability, durability, fair working conditions, human rights, supplier stability, quality and life cycle costs.
What is ISO 20400?
ISO 20400 is an international guidance standard for sustainable procurement. It helps organisations integrate sustainability into procurement strategies, processes and supplier relationships.
How can companies implement sustainable procurement?
Companies should analyse categories, define sustainability goals, integrate relevant criteria into tenders, evaluate suppliers, consider life cycle costs and measure progress through KPIs.
Why are life cycle costs important?
Life cycle costs show that a low purchase price is not automatically economical. Use, energy consumption, maintenance, repairs and disposal can be more relevant over the full useful life.